Strong U.S. employment gains expected in March; jobless rate seen falling to 3.7% -Breaking
[ad_1]
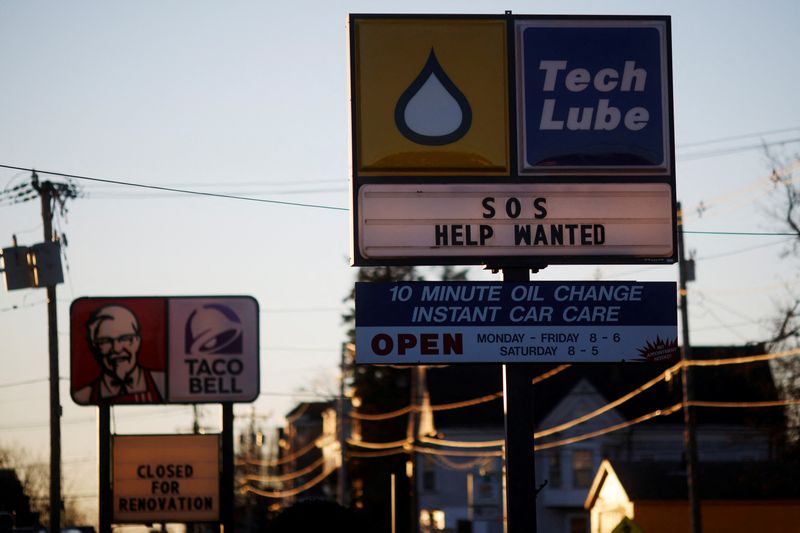 © Reuters. FILEPHOTO: A sign that reads “Sos Help Wanted” at an automotive oil-change store in Brockton (Massachusetts), U.S.A, January 4, 2022. REUTERS/Brian Snyder
By Lucia Mutikani
WASHINGTON (Reuters] – U.S. jobs growth was strong, falling to 3.7% in March. Wages reaccelerated, which could position the Federal Reserve for a substantial 50 basis point increase in interest rates in May.
Inflation, tighter monetary policy, and Russia’s ongoing war against Ukraine are all factors that could be affecting the economy’s momentum. Friday’s Labor Department Employment Report would reflect this solidity. It will also highlight economic strength as it faces increasing headwinds.
Last month, the Fed raised its policy rate 25 basis points. This is their first increase in over three years. Fed Chair Jerome Powell stated that policymakers are increasing their hawkish rhetoric and the U.S. central banking must act “expeditiously” in raising rates, possibly even more aggressively to prevent high inflation becoming entrenched.
For the Fed to decide on its May 3-4 policy decision, it will need March’s employment data and April 12’s consumer price data.
Sam Bullard is a senior economist. He stated, “The broad perspective of a tight labour market, will continue into March.” Wells Fargo Charlotte (NYSE:), North Carolina. The Fed will be looking into this, alongside inflation and future inflation, when they decide to possibly increase their policy tightening.
A survey of establishments will likely show that nonfarm employment increased by 490,000. This is after it grew by 678,000 in February. According to a Reuters poll, economists. There were estimates as low as 200k and as high as 700,000.
Even though March’s projected job growth is slower than February’s strong pace, it will still fall within the 424,000-678,000 range from the six previous months.
The expected upward revisions of February’s number could offset a smaller March figure. In recent months, large upward revisions have occurred in the payroll data.
The sharp drop in COVID-19 infection rates is driving demand for employment. This has led to restrictions being removed across the country. It is unclear if the Russia-Ukraine War, which has driven gasoline prices to over $4 per gallon has had an impact on the labor markets.
Last month’s job gains were expected to be across all sectors.
Simona Mocuta chief economist at, stated that “any miss in the payrolls numbers won’t necessarily be a story about crumbling labor demand.” State Street Global Advisors Boston.
On Tuesday, the government released data showing that there was a record 11.3million job opportunities. The gap between the workers and the employers stood at 3.0%. It is close to December’s post-war peak of 3.2%. It is anticipated that the labor pool will continue to grow in March.
WORKERS COMING BACK
According to a report from global outplacement firm Challenger, Gray & Christmas on Thursday, the skyrocketing cost of living was “causing workers who were depending on savings or investments to seek out paid employment.”
Inflation rose by 40% in February, the highest level in over 40 years. As companies compete to hire scarce workers, they are helping to boost inflation.
After being flat in February, the average hourly wage is expected to rebound by 0.4%. This would increase the annual growth to 5.5%, from 5.1% in February. It is possible that monthly wage increases could fall below what was expected. This week includes the 12th day in the month. Data are collected for the Employment Report.
Kevin Cummins, chief U.S. economist, NatWest Markets, Stamford, Connecticut, stated that “the 15th of each month fell outside of the reference week,” raising the chances of another below-trend outcome.
Most likely, the average workweek remained steady at 34.7 hours.
Detail of the household survey from which the unemployment rate was calculated is expected to reflect the strength of the establishment survey. From 3.8% in February, the jobless rate will drop to 3.7% by 2020.
The trend is not surprising considering that the labor force participation, the ratio of Americans over the age of 18 who either have or are searching for a job, has increased from 62.3% to February. It was at its highest point since March 2020.
After a short inversion of this week’s widely followed U.S. Treasury yield curve, the employment report will further reduce financial market concerns about a possible recession.
According to economists, the Fed’s large holdings of Treasuries (and mortgage-backed securities) made it difficult for them to see the movement in the yield curve. Real yields, however, remained negative. Others suggested that the Treasury yield curve, which is two-year/five year in duration, was a more reliable indicator of a possible future recession. This segment hasn’t inverted.
Padhraic Garvey from ING New York, said that inversion, whether it is true or false, does not indicate an imminent recession. A recession will only be coming in two to four years if the curve is inverted. There are many things that can occur in this time period.
[ad_2]