U.S. stocks, bonds flash diverging signals as volatile first quarter ends -Breaking
[ad_1]
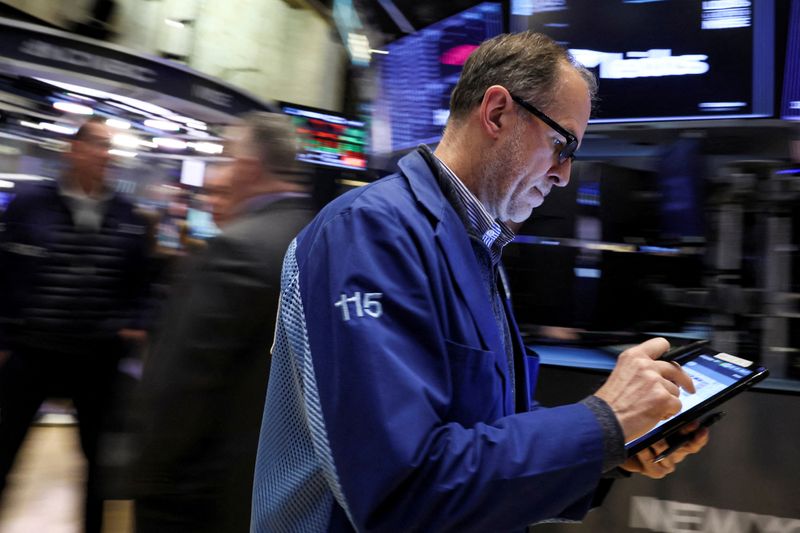 © Reuters. FILE PHOTO – Traders are seen working on the New York Stock Exchange’s floor in New York City (U.S.A.), March 29, 2022. REUTERS/Brendan McDermid/File Photo
By David Randall
NEW YORK, (Reuters) – Which market is right?
The first quarter 2022 is over and the U.S. bond and stock markets seem to have drastically differing views of the future growth outlook. Investors will need to choose which view they prefer.
It has rebounded from an almost-13% plunge and closed the quarter at 4.9%. The rebound has been defiant to worries about tighter macroeconomic policy and increased geopolitical instability due to the war in Ukraine. Many stock investors have even shrugged off a brief inversion of a closely watched section of the U.S. Treasury yield curve – a phenomenon that has predicted past recessions.
Investors in bonds seem more optimistic about the economy than ever, with the ICE(NYSE:) BofA index predicting its worst year yet. The BofA index is on course for the worst start since 1999. Its fear that the Fed could cause recession by tightening monetary policies to counter rising inflation. The benchmark 10-year Treasury yield is up by 81 basis point this quarter. They are near their highest levels since May 2019!
The, which is viewed by investors as an indicator of market fear, stands just below its lowest point of the year. Investors are pinning stocks’ reversal on everything, from quarter-end balancencing to buying retail investors. The ICE BofAML MOVE Index, which measures Treasury yield volatility and is elevated, remains high.
Edward Al Hussainy is a senior currency and interest rate analyst at Columbia Threadneedle. “Rates market are consistent in telling the story that the Fed will do some damage, while (while) risks markets haven’t really done a great job pricing any damage to growth outlook,” he said. “One of these stories was wrong.”
Different roads https://fingfx.thomsonreuters.com/gfx/mkt/akvezjnjypr/Pasted%20image%201648745384426.png
Investors have been arguing about the yield curve. Rates for 2-year Treasuries rose briefly above rates for 10-year Treasuries this week.
This inversion, which has occurred six times before the recessions of 1978 and 1979 according to Truist Advisory Services’ data. Some investors, however, have given a broad range of reasons why the signal’s predictive power may not apply this time, including the potentially distortive effects of the Fed’s massive COVID-19 stimulus on rates markets.
In any case, recessions have followed past inversions with an average lag of 16 months, and the S&P 500 has averaged an 11% gain in the 12 months following inversions, Truist’s data showed.
Overall, the S&P 500 has lost an average of 8.8% during the four recessions since 1990, according to CFRA data.
“We would take this (equity) rally as a sort of a gift,” said Sameer Samana, senior global market strategist at Wells Fargo Investment Institute. (NYSE:). “If you weren’t able to reduce your exposure to some of the speculative areas of the market before the correction, now is your time.”
UBS Global Wealth Management’s chief investment officer Mark Haefele warned investors to not over interpret the excitement in stocks or the woes in bond markets. Still, the firm has scaled back its outlook for global earnings growth and now sees a more modest upside for stocks with a year-end target of 4,700 on the S&P 500. On Thursday, the index was at 4,530.41.
Others have pointed out that the gap between yields on the 3-month and 10-year Treasuries – another closely followed measure – is positive by approximately 180 basis points.
That’s a sign there is still room for the Fed to shift gears before the market starts to price in a recession, said Gary Cloud, a portfolio manager at Hennessy Funds.
Cloud stated that although policymakers said they would raise rates up to 50 basis points at a single meeting, and investors have priced in around 200 basis points this year of tightening, the Fed “does not want to tighten enough that it causes recession.”
Some are skeptical, though, that the Fed is able to create a soft landing.
Tim Murray is a T. Rowe Price capital market strategist who has moved into commodity and other defensive areas of the stock exchange while increasing his allocations to Treasuries with a longer duration. He believes that these assets will flourish in a downturn.
Murray stated that once the Fed begins hiking there is a high chance of a recession within the near future. “I feel that the investors aren’t worried about this,” Murray said.
Rocky quarter for stocks, bonds as Fed begins rate hikes https://graphics.reuters.com/USA-MARKETS/QUARTER/egpbkblozvq/chart.png
[ad_2]