Expectations of more aggressive Fed crush U.S. yield curve -Breaking
[ad_1]
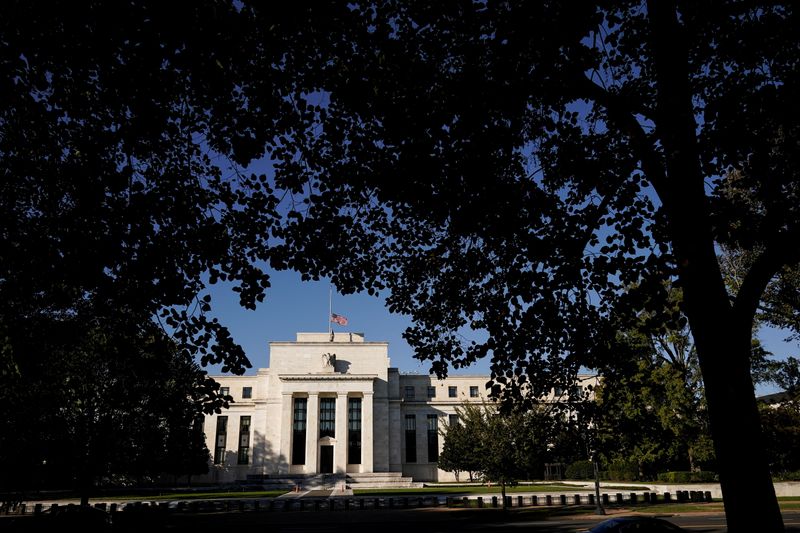 © Reuters. FILEPHOTO: Washington, U.S.A, October 20, 2021. REUTERS/Joshua Roberts
Gertrude Chavez, Dreyfuss and Karen Pierog
(Reuters) – Investors try to gauge what a sudden flattening in the U.S. yield curve might mean about growth expectations and the Federal Reserve’s willingness to tighten monetary policy against rising inflation.
On Thursday, yields on 20 year Treasuries rose more than those on 30 year bonds several times. Analysts attributed this move to technical factors such as higher demand for liquid, 30-year bonds, and expectations of a Fed that is more hawkish.
Inversely, yields change with bond prices.
To predict investor expectations regarding U.S. growth, and monetary policy, market participants monitor the yield curve. Inverted curves have at times presaged https://www.reuters.com/article/us-usa-economy-yieldcurve-explainer/countdown-to-recession-what-an-inverted-yield-curve-means-idUSKBN1ZR2EX recessions and some analysts said the slope starting at the short end of the yield curve matters most for the economic outlook.
Dan Belton of BMO Capital Markets Chicago, fixed income strategist said “I wouldn’t take the 20/30 years yield inversion [as a signal] for a recession.” The move is technical in nature, as it’s not within the yield curve. A further advantage is that no benchmark rate has inverted.
Belton explained that “the market has priced an even steeper rate rise path which has caused all yield curves to flatten although not invert.”
Analysts said that expectations that inflation would rise faster will push short-term yields higher, but long-term yields fell as market wagers that the Fed will not raise rates as fast as they had previously predicted.
Roberto Perli of Cornerstone Macro, Head of Global Policy, stated that “the market believes the Fed will increase rates sooner than originally thought.” This will eliminate any chance of inflation, which will make it less likely for them to need to raise rates in the future.
Fed policymakers will announce at their Nov. 3 meeting plans to reduce the $120 billion monthly purchase of Treasuries by the central bank.
Due to the yield moves the gap between 10- and 2-year note prices narrowed by as much as 97.7 base points on Thursday. It is now the flattest curve since August. But it is still not inverted. With 73.4 basis point, the 5-year note-to-30 year bond yield curve is at its lowest level since March 2020.
The spread has not been as flattened in recent weeks, starting this week at 158.6 base points and currently hovering around 151 basis points.
It is an international phenomenon. The Australian bond market was hit by Mayhem on Thursday when a flood of selling drove three-year yields up to 1.17%. This is an astonishing 39 basis point increase in two sessions, and it’s the largest such movement since 2009.
In Canada, Germany and elsewhere where central banks expect to tighten their monetary policies at a quicker pace than they previously expected, yield curves are also showing flattening.
Uncertainty over Jerome Powell’s future term as Fed Chair and the possibility of a central bank that is more hawkish are two other factors contributing to the flattening curve, according to Cornerstone Macro reports on Thursday.
According to it, “We could see partial reversal in the current curve flattening” if Powell was reaffirmed. We say partial because persistent inflation doubts will still remain. It will be necessary to have lower inflation in order for the inflation rate to significantly reduce.
Rate hikes are expected.”
[ad_2]