Explainer-The Libor era nears its end -Breaking
[ad_1]
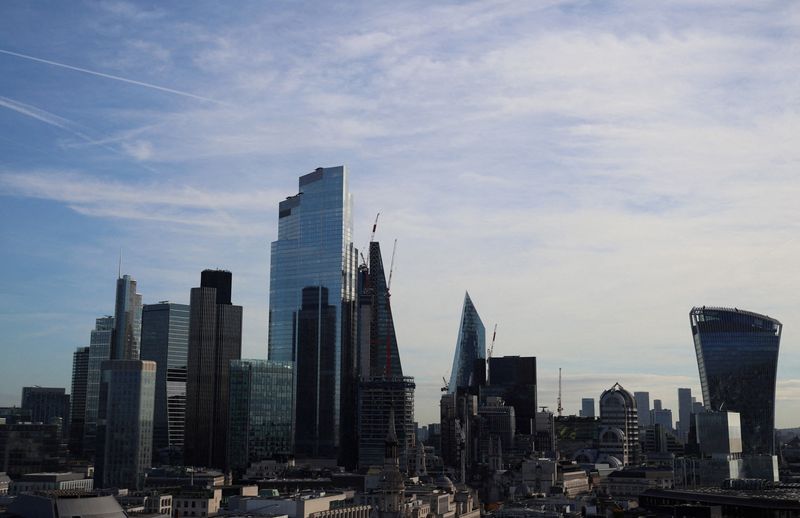 © Reuters. FILEPHOTO: London’s City of London Financial District is seen October 22nd, 2021, in London. REUTERS/Hannah McKay
John McCrank and Karen Brettell
NEW YORK, (Reuters) – Libor or the London Interbank Offer Rate will be no longer used to make new loans and derivatives. This is the most significant market shift since 1999’s introduction of the euro. It was linked to $265 trillion worldwide at the time of its creation.
What is LIBOR and WHY IS IT REPLACED
Libor was once called the most important number in the world. It is calculated from quotes received from banks about how much it would be to borrow short-term money from each other. It was established in 1986, although it is a rate that dates back to 1969. Since then, it has been used for reference rates on a wide range of financial products including student loans, corporate loans, and mortgages.
Libor became discreditable after 2008’s financial crisis. Authorities discovered that traders had manipulated it. There was a call for reform to replace this tarnished rate. A number of global banks were fined.
What IS Replacement Libor?
Libor’s 35 possible permutations include five currencies: the U.S. dollars, British pound, euro, Swissfranc, Japanese and Japanese yens. Libor tenors are the remaining time before an agreement expires. These tenors can be linked to U.S. dollars, but will not end until June 2023 in order to let most existing or “legacy” contracts mature.
Alternative rates are replacing Libor, and central banks prefer to recommend those that are based upon actual transactions. This makes them more difficult to manipulate. [L1N2TC0XL]
WHAT RISKS AVOIDING?
After Jan. 1, the vast majority of Libor Tenors won’t be released. However, U.S. Dollar tenors may continue until June 2023. Analysts warned that this could pose legal challenges for those companies with outstanding debt.
New York’s state law allows “tough legacy” contracts to continue in force. These are those which expire after June 20,23 without fallback language that specifies an alternate rate. They can be modified only by using the Secured Overnight Funding Rate recommended by U.S. Federal Reserve. Similar legislation is currently being worked on by Congress.
Regulators in the UK also announced that six sterling and one yen Libor rate will be maintained in “synthetic”, which is the Bank of England’s Sterling Overnight Index Average or SONIA combined with fixed spread, for a period of one year. This gives market participants greater time to switch to different rates for contracts.
LIBOR LIQUIDITY
Many of the U.S. dollars derivatives market have already switched to SOFR. For short-term contracts that are used to speculate on or hedge against changes in interest rates, there is still a large amount of exposure based upon Libor. CME SOFR futures volume graphic.
These contracts are expected to lose liquidity, making it more difficult for investors to hedge Libor-based exposures. When placing bets about future rates, investors will need to adapt to other instruments.
LOAN PRICE QUESTIONS
Pricing challenges will also arise from the shift to SOFR (from Libor). Borrowers and loan issuers want to be able to access credit benchmarks that can adjust to changes in credit market conditions.
SOFR is calculated using the U.S. Repurchase Agreement Market, which does not have credit risk but may drop during periods of stress. Libor is a measure of bank borrowing costs. It rises in times of stress.
In order to adapt, lenders are pricing loans at a spread of SOFR. If credit stresses unexpectedly occur, this spread can underprice risk.
[ad_2]