Inside the Off-Market Real Estate Relationships Behind Eric McNeil’s Strategy
A South Florida condominium project has a legal starting line that almost nobody outside the business ever sees. Under section 718.502 of the Florida Statutes, a developer must file the documents required by sections 718.503 and 718.504 with the state’s Division of Florida Condominiums, Timeshares and Mobile Homes before a contract to buy a unit becomes enforceable against the purchaser. Until that filing is done, the buyer can void the contract at any point before closing. There is no billboard attached to the filing, no press release and no hoarding on the site. It is a paperwork event, and often the only thing that has happened.
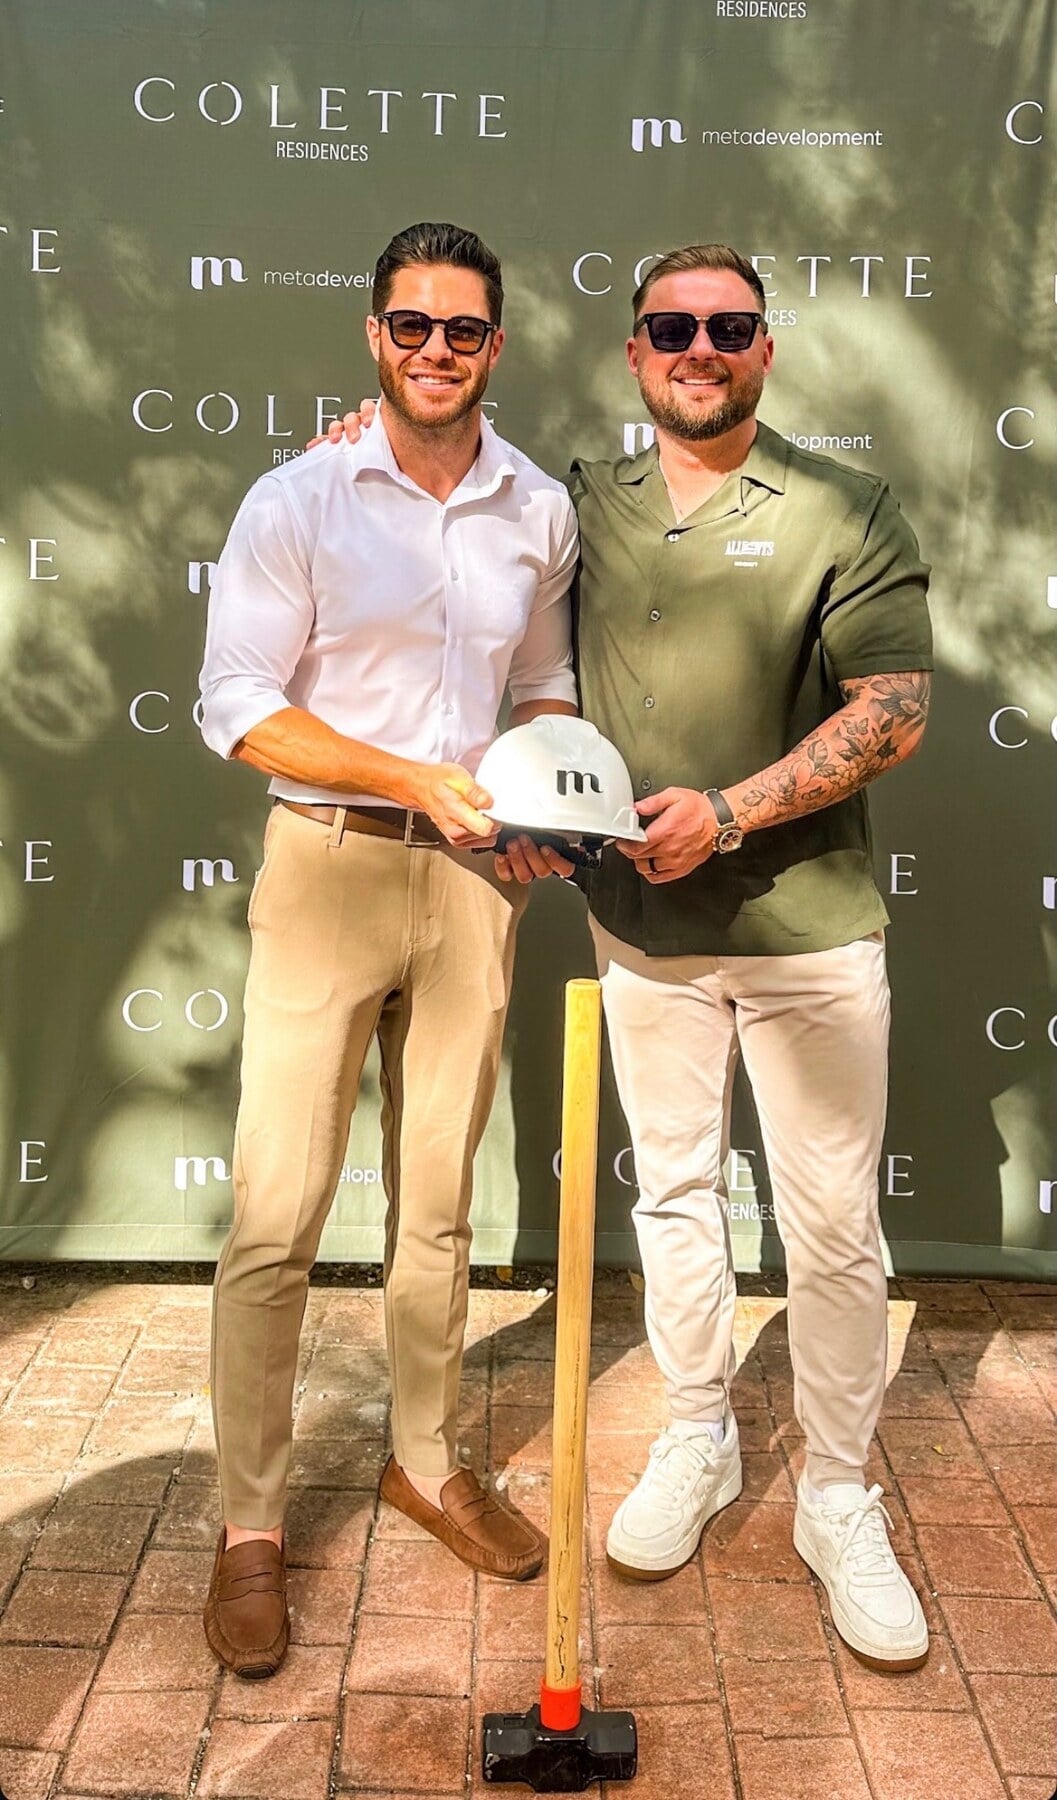
Between a project’s earliest stages and its broader public launch, there can be a window in which opportunities are shared through developer relationships and private networks rather than broadly marketed to the public. Eric McNeil’s work alongside luxury developers in the Miami to Palm Beach corridor often focuses on these developer-direct and off-market opportunities. Most accounts of it are written from the buyer’s chair. The sponsor’s side is the more interesting one, because a developer who keeps a release quiet is choosing, for a period, to sell to fewer people than he could.
The launch is the expensive part
Going public with a tower is not a switch that gets flipped. It is a capital programme that runs well ahead of revenue.
Renderings, a physical model, a furnished model residence, a brand identity and a sales gallery all get paid for before a single contract is signed. Bisnow has reported Miami condominium developers spending between five and eight million dollars on a sales gallery alone, with one sponsor building a centre of roughly 22,000 square feet, and galleries taken on leases of two to five years so that they last the whole sales run. A gallery of that kind is a set built to sell a building that does not exist, and it has to hold the attention of brokers with four other openings to show that season.
Then there is the co-operating commission. New development in South Florida pays outside brokerages considerably more than a resale does, because the sponsor is buying reach across a whole broker population rather than a single introduction. When presales slow, that cost tends to rise rather than fall. The Miami market analyst Peter Zalewski reported in May 2025 that South Florida condominium developers were increasing commissions and easing deposit requirements at the same time, with condominium listings across the region at their highest level since 2016.
A quiet phase spends none of it. A sponsor who places part of an early release through a short list of known counterparties has moved inventory without opening the gallery and without paying for reach he did not need yet.
What a price list does once it is public
The second cost is harder to put a figure on, and it is the one experienced sponsors talk about first.
A published price list is a reference point. It circulates through broker networks within hours, it gets forwarded well beyond the people it was sent to, and it gets set against every other opening in the submarket. Once it exists, every move a sponsor makes afterwards is read as a signal. Raising prices between phases tells the market the building is working. Quietly improving terms tells it something else, and the market hears the second message faster than the first.
A quiet phase leaves no such record. Pre-construction purchase contracts are not ordinarily recorded in the county’s public files, so the price a buyer agreed becomes visible only when the deed is recorded at closing, which in a tower is three or four years later. By then the building is finished and the number is history. Working through a private list, a sponsor can price the first tranche of a release, watch how a small group of serious buyers responds, and adjust before anything has been committed to a document that travels.
That is pricing power in its plainest form: finding out what a building is worth without telling the market what was asked for it.
The number the lender is watching
Construction lenders have long conditioned funding on a share of the units being under contract with hard deposits attached. The threshold has moved with the credit cycle, and some well-capitalised sponsors now break ground before reaching it, on the reasoning that visible progress on site sells the rest. The principle survives either way. Presales are the evidence a lender uses to decide whether a project is real.
Which makes the composition of an early release matter more than its size. A sponsor needs contracts that will still be standing at delivery, not contracts that look impressive in a monthly report and evaporate when the market turns. The quiet phase is where he assembles that base out of counterparties whose closing behaviour he can predict, before he opens the doors to a population he knows nothing about.
Pace tells him something too. A release that sells out in a fortnight is evidence the sponsor priced it wrong, and he would rather learn that from a list of twenty than from a public launch he cannot take back.
Why a particular name ends up on the list
Seen from the sponsor’s chair, the list is short for a reason that has nothing to do with generosity. He has spent the quiet phase buying control of information, and each additional person on the list is a route by which he loses it.
Selection therefore runs on two questions. Will this buyer close on the terms agreed, without reopening them the first time the market wobbles. And will anything they learn about the project travel. A delivery date that has moved, a floor plate still under revision, a decision about how the next phase will be handled: all of it is worth something to a competing sponsor two blocks away, and none of it should be circulating.
McNeil’s standing in the corridor is the accumulated answer to those two questions across a series of projects. His relationships across capital, sport and entertainment are what put his name into the conversation in the first place, since a developer assembling a private list asks the people around him who is credible, and the people around him are rarely property people. What keeps the name there is the duller half of the job. Miami-Dade and Palm Beach County hold a limited number of sponsors building at this level, they talk to one another, and a leak takes about a week to trace back to whoever let it go.
What the sponsor gives up, and when the window shuts
Staying quiet is a trade, and it costs the sponsor real things. A broad launch generates momentum that no private list can manufacture. It produces price discovery across a wide and unfamiliar buyer population rather than a narrow and friendly one. It reaches international purchasers who would otherwise never encounter the project, and in Miami that population accounts for a large share of new construction demand. A sponsor who stays quiet too long can arrive at his construction financing with a thin contract base, all of it drawn from the same few circles, and no honest read on what the wider market thinks.
The sponsors who handle it well treat the quiet phase as a first act rather than as a strategy. They use it to set price, to secure a core of contracts that will actually close, and to produce the one thing money cannot buy on launch day, which is a building that already looks partly spoken for when the billboard goes up. Then the window shuts, the gallery opens, and the project belongs to the broker networks and the price list like every other project in the submarket.
What survives the window is the strength of the relationship built through it. McNeil’s approach treats that relationship capital as an asset, which is why his work remains concentrated in the South Florida corridor rather than spreading broadly across markets. Developer-direct access is built over time through credibility, consistent execution and completed transactions, and there is no shortcut for establishing that trust.
This article is for informational purposes only. It is not an offer to sell or a solicitation of an offer to buy any security, and it is not investment, financial, legal or tax advice. Real estate and private market investments carry risk, including loss of principal, and nothing described here is a prediction of future results. Readers should consult their own licensed advisers before making any financial decision.